What is the Market overview of the Scrap Metal Recycling Market?
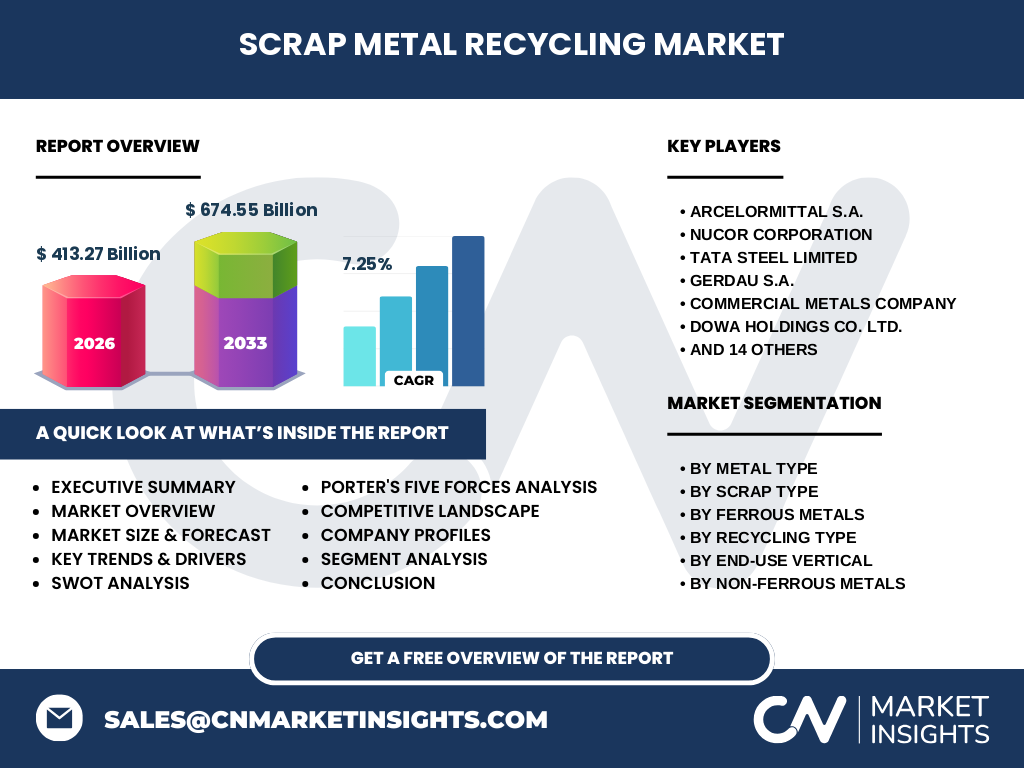
Our analysis indicates that the Scrap Metal Recycling Market is valued at $413.27 Billion in 2026, serving as an indispensable pillar of the global circular economy. The industry encompasses the recovery, sorting, processing, and re-melting of ferrous metals like steel and carbon steel, alongside non-ferrous commodities including aluminum, copper, and precious metals. By bridging raw material deficits for primary manufacturers, the sector significantly mitigates industrial carbon footprints and conserves diminishing natural mineral reserves.
Key market drivers, restraints, challenges, and opportunities shaping Scrap Metal Recycling Market
Growth is heavily propelled by stringent environmental regulations from bodies like the EPA and EU directives targeting industrial emissions. However, logistical bottlenecks in collection networks and volatile metal price fluctuations present persistent operational restraints. Substantial opportunities lie in upgrading processing facilities with advanced sensor-based sorting technologies to extract higher-purity secondary raw materials from complex post-consumer waste streams.
Emerging trends and growth patterns in Scrap Metal Recycling Market
The sector is witnessing a rapid transition toward automated processing using AI-driven optical sorting systems to separate non-ferrous grades like brass, bronze, and zinc. Major operators are aggressively investing in low-emission electric arc furnaces (EAF) to process scrap efficiently. These industry trends reflect a broader corporate imperative to secure localized, decarbonized supply chains ahead of tightening global carbon border adjustment mechanisms.
How did COVID-19 impact the Scrap Metal Recycling Market and what is the recovery trajectory?
The pandemic induced severe supply chain disruptions, causing temporary shutdowns of automotive plants, construction sites, and manufacturing hubs that traditionally feed industrial scrap into the ecosystem. Despite these initial setbacks, the post-pandemic recovery trajectory has been exceptionally robust, fueled by aggressive government stimulus packages directed at infrastructure renewal and green energy transitions, accelerating overall market momentum.
Competitive Benchmarking: Major players and strategic dynamics
Market concentration is moderately fragmented, featuring industrial powerhouses such as ArcelorMittal S.A., Nucor Corporation, and Sims Metal Management Limited alongside regional heavyweights like SA Recycling LLC and European Metal Recycling Limited. Strategic dynamics center on vertical integration, where steelmakers acquire scrap yards to secure captive raw material feeds, insulating their operations against virgin ore price volatility.
Executive Summary of the Scrap Metal Recycling Market
Our comprehensive research projects the Scrap Metal Recycling Market to expand from $413.27 Billion in 2026 to reach $674.55 Billion by 2033, reflecting a robust CAGR of 7.25%. This expansion is underpinned by escalating industrialization, strict decarbonization mandates, and the rising demand for secondary aluminum and copper across automotive, aerospace, and energy sectors.
Market Forecast and Growth Trajectory (2027 to 2033)
The data suggests a stellar compound annual growth rate of 7.25% throughout the 2027-2033 forecast window, driving total market valuation from $413.27 Billion to $674.55 Billion. This acceleration is driven by mounting pressure on heavy industries like mining, oil and gas, and heavy equipment manufacturing to achieve net-zero targets by utilizing high-grade recycled ferrous and non-ferrous inputs.
Segmentation Analysis of the Scrap Metal Recycling Market
The market is systematically segmented by metal type (ferrous including steel and cast iron; non-ferrous including aluminum, copper, lead, zinc, nickel, tin, brass, bronze, and precious metals), scrap source (industrial, post-consumer, construction and demolition), recycling method (shearing, shredding, baling), and end-use vertical spanning automotive, shipbuilding, construction, aerospace, and energy industries.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with industrialized regions like North America and Europe maintaining dominant market shares due to established regulatory frameworks and mature manufacturing bases. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by massive infrastructure developments, rapid urbanization, and extensive shipbuilding and construction activities in emerging economies.
In-depth Regional Review of Key Geographies
North America benefits from highly consolidated scrap processing networks managed by key players like Schnitzer Steel Industries Inc. (Radius Recycling) and Upstate Shredding - Weitsman Recycling LLC. In contrast, European markets are governed by rigorous circular economy action plans that mandate higher recycling quotas, forcing automotive and heavy machinery sectors to integrate closed-loop recycling protocols.
Company Profiles and Strategic Positioning
Leading industry participants leverage distinct operational strategies. Commercial Metals Company and Gerdau S.A. focus on mini-mill optimization, pairing EAF steelmaking directly with localized scrap yards. Meanwhile, global operators like Tata Steel Limited and Hindalco Industries Limited prioritize green-metal procurement to satisfy stringent Scope 3 emissions reporting required by downstream automotive and packaging clients.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to the dispersed nature of scrap generation across construction and automotive sectors. However, buyer power is high among major steel mills that demand strict quality specifications. Threat of substitution from virgin raw materials is diminishing as carbon taxes rise, while competitive rivalry among established recyclers drives continuous technological automation.
SWOT Analysis of the Scrap Metal Recycling Market
Strengths include established global collection logistics and significant energy savings compared to primary ore extraction. Weaknesses involve high capital expenditure required for advanced sensor-sorting machinery. Opportunities lie in expanding EV battery and precious metal recycling streams, while major threats include cross-border trade restrictions on scrap exports and fluctuating commodity prices.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with scrap generation across demolition, manufacturing, and consumer discard. It flows through localized collection yards, where operators utilize shearing, shredding, and baling to process materials. Processed metals are then transported via major logistics hubs to end-users in the automotive, aerospace, and energy sectors for remelting into high-specification alloys.
Investment Insights and High-Potential Areas
Investors should direct capital toward automated non-ferrous separation facilities and proprietary digital platforms that optimize scrap yard inventory management. Companies possessing advanced processing capabilities for high-value alloys, electronics, and aerospace-grade titanium are positioned to capture outsized margins as industrial demand for certified green metals accelerates.
Conclusion and Key Takeaways for Market Stakeholders
The Scrap Metal Recycling Market represents a highly lucrative, mission-critical sector transitioning toward advanced automation and strict environmental compliance. With market value scaling toward $674.55 Billion by 2033, stakeholders must embrace technological modernization, strategic regional consolidation, and sustainable processing methods to secure long-term competitive advantage.
Research Methodology for Baseline Estimates
Our baseline estimates and market sizing are rigorously triangulated by combining primary stakeholder interviews with scrap yard operators, secondary trade registry data from international metal associations, and macroeconomic indicators. Regression models correlate industrial manufacturing indices with historical scrap recovery rates to formulate accurate 7.25% CAGR projections.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Scrap Metal Recycling Market across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include potential volatility in informal scrap collection economies and sudden geopolitical shifts impacting cross-border ferrous and non-ferrous trade tariffs.
Recent Developments, Strategic Partnerships, and Corporate Moves
Recent industry developments highlight major players like Harsco Corporation and Kuusakoski Group Oy forming strategic joint ventures with automotive OEMs to establish closed-loop aluminum recycling programs. Furthermore, acquisitions among firms like TKC Metal Recycling Inc. and Metallon Recycling Pte Ltd. emphasize a broader trend toward regional processing consolidation and capacity expansion.